


 :

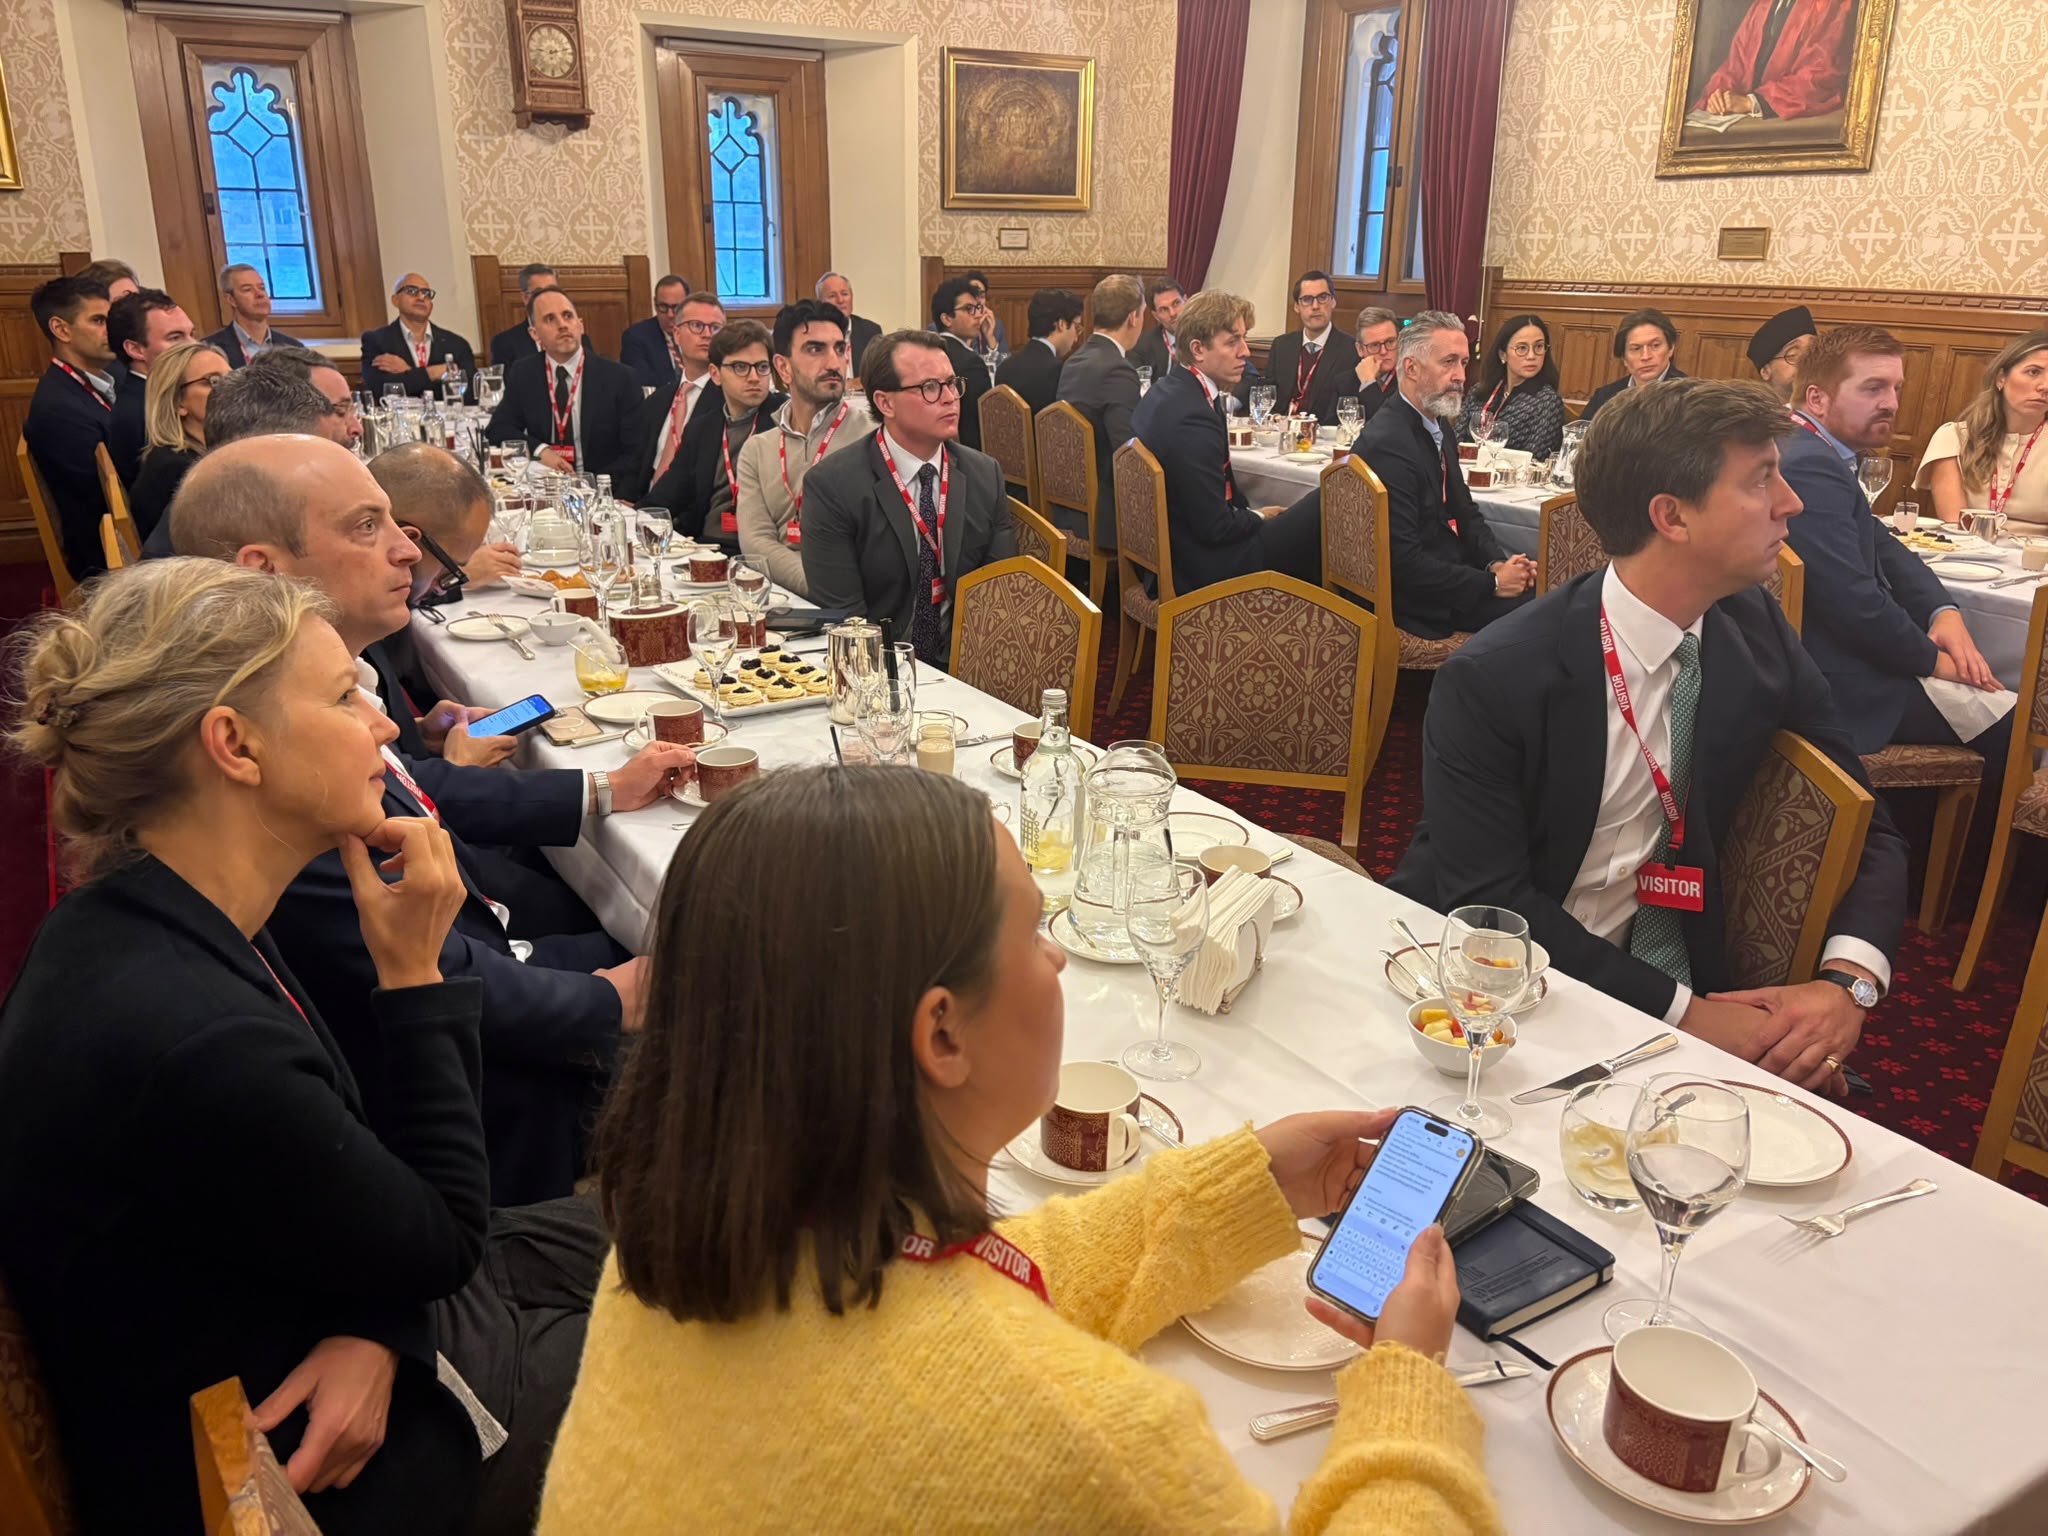
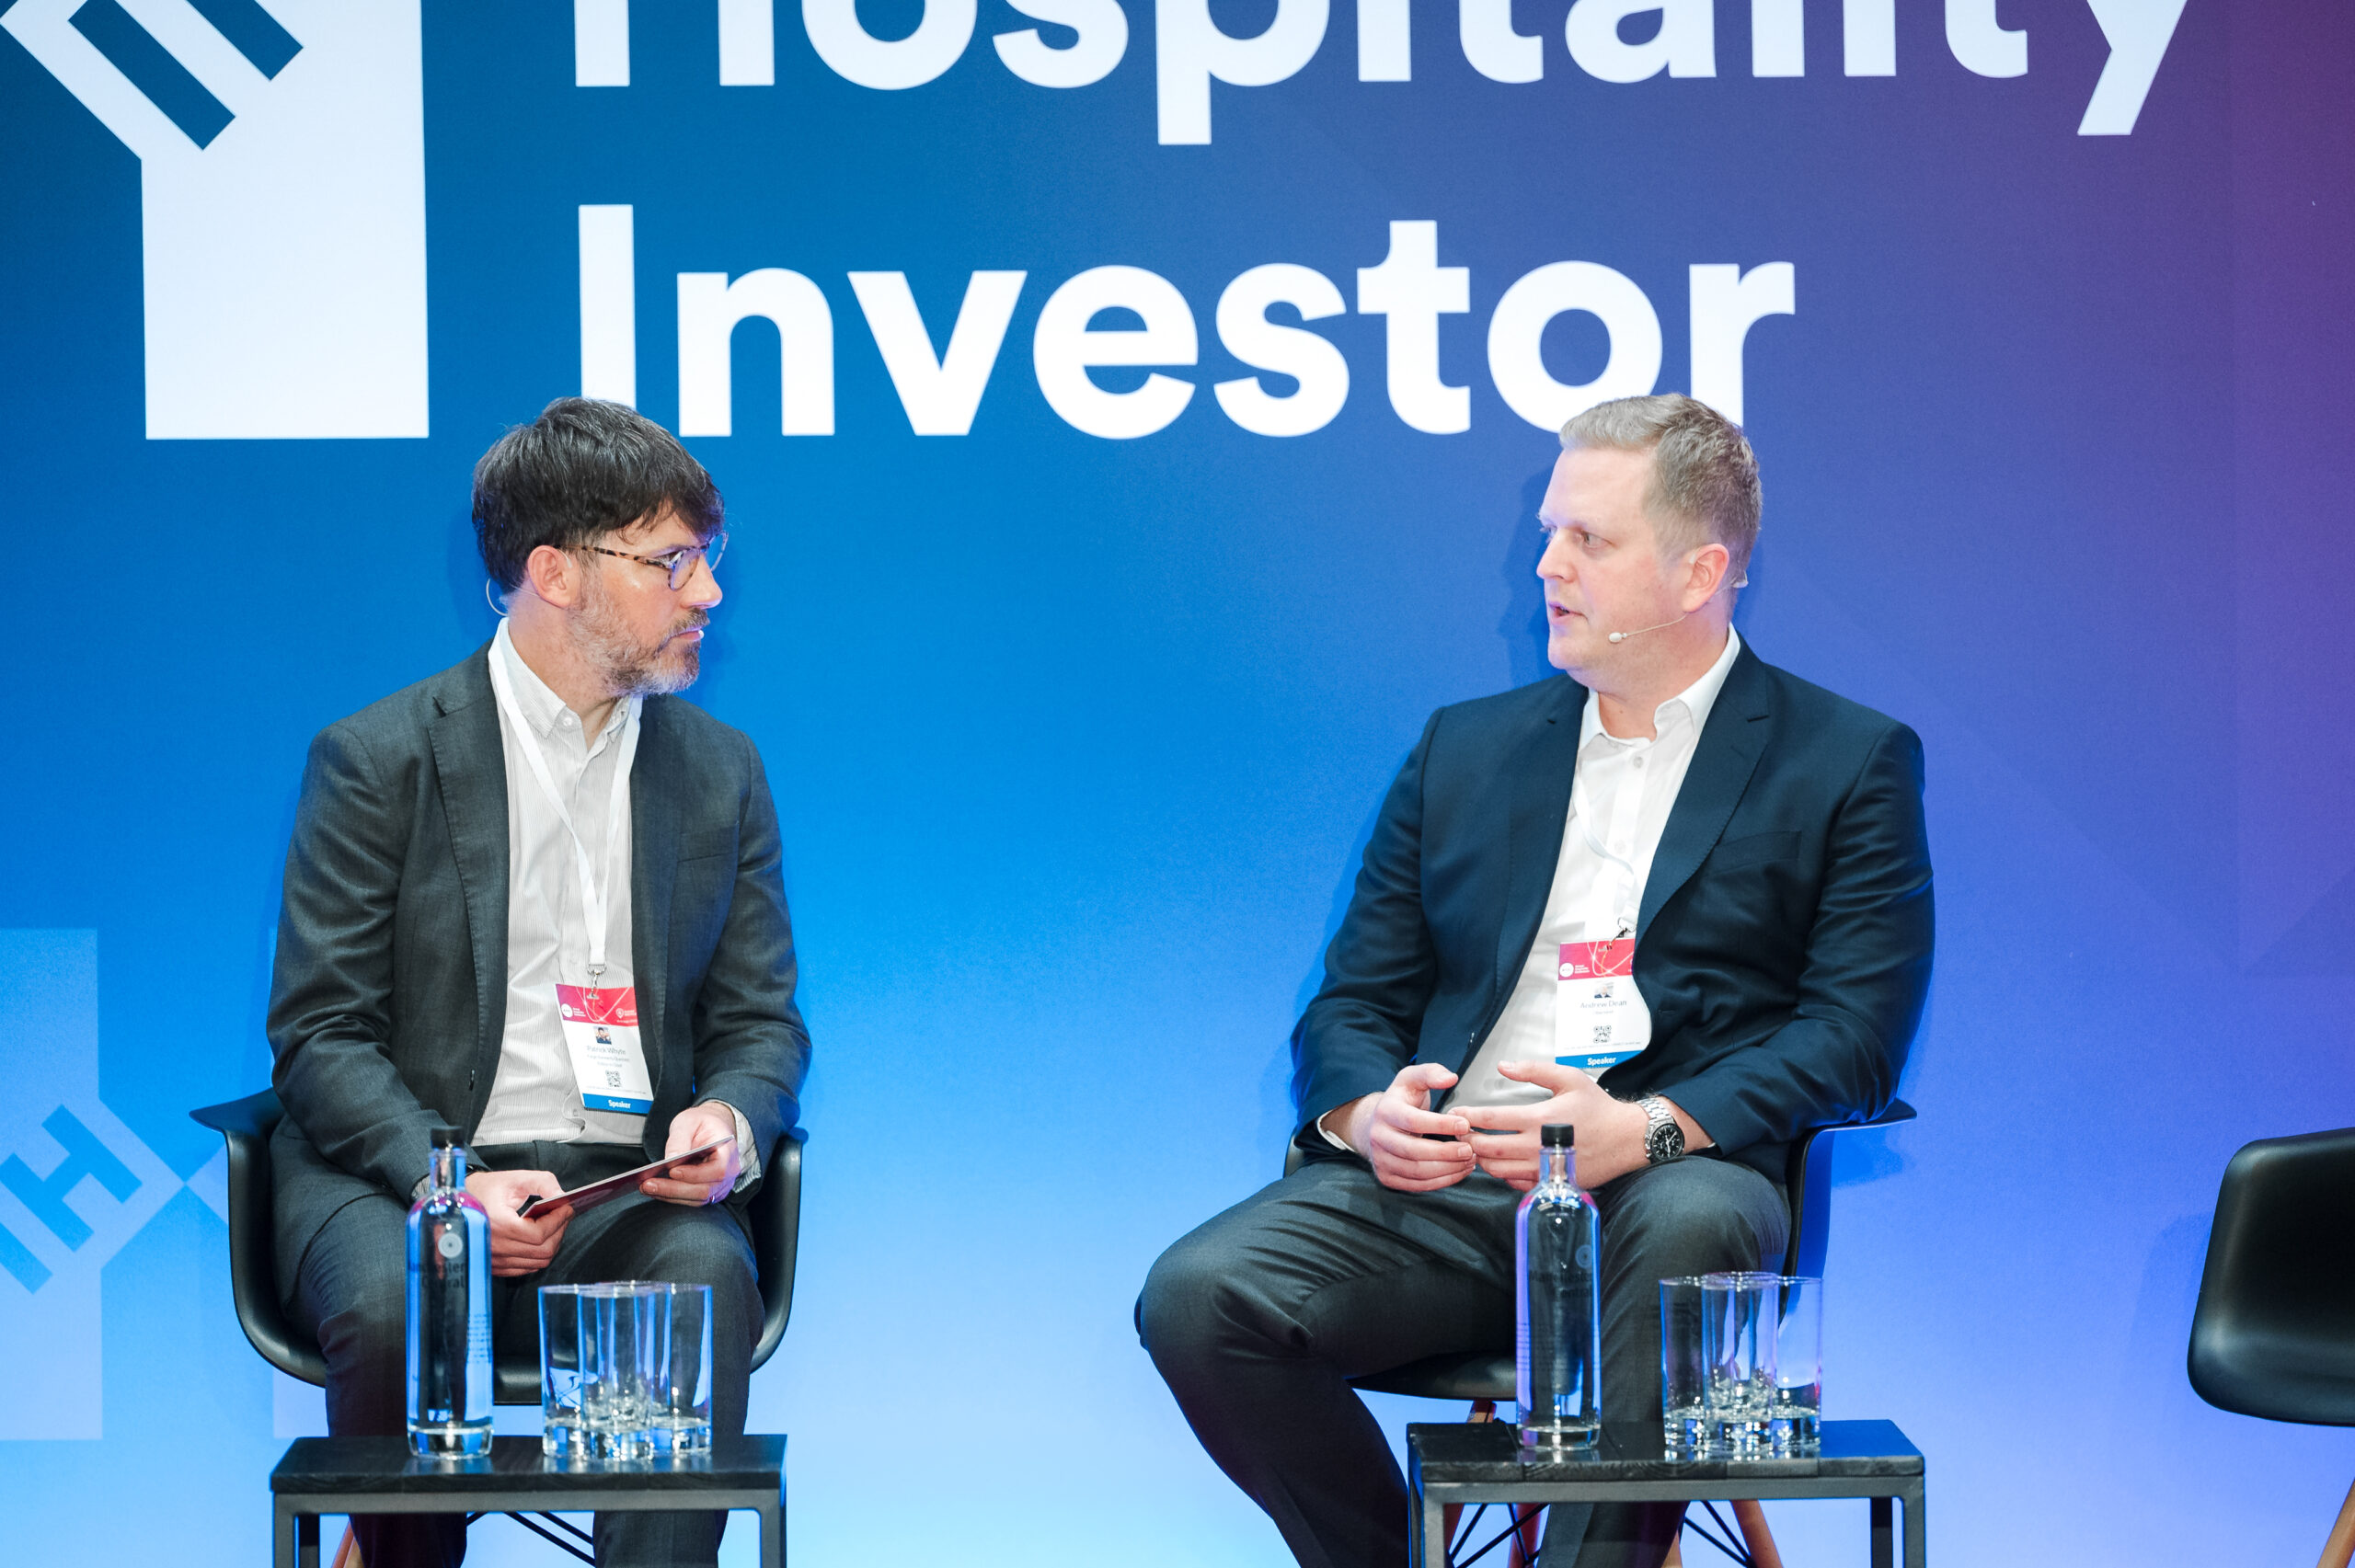
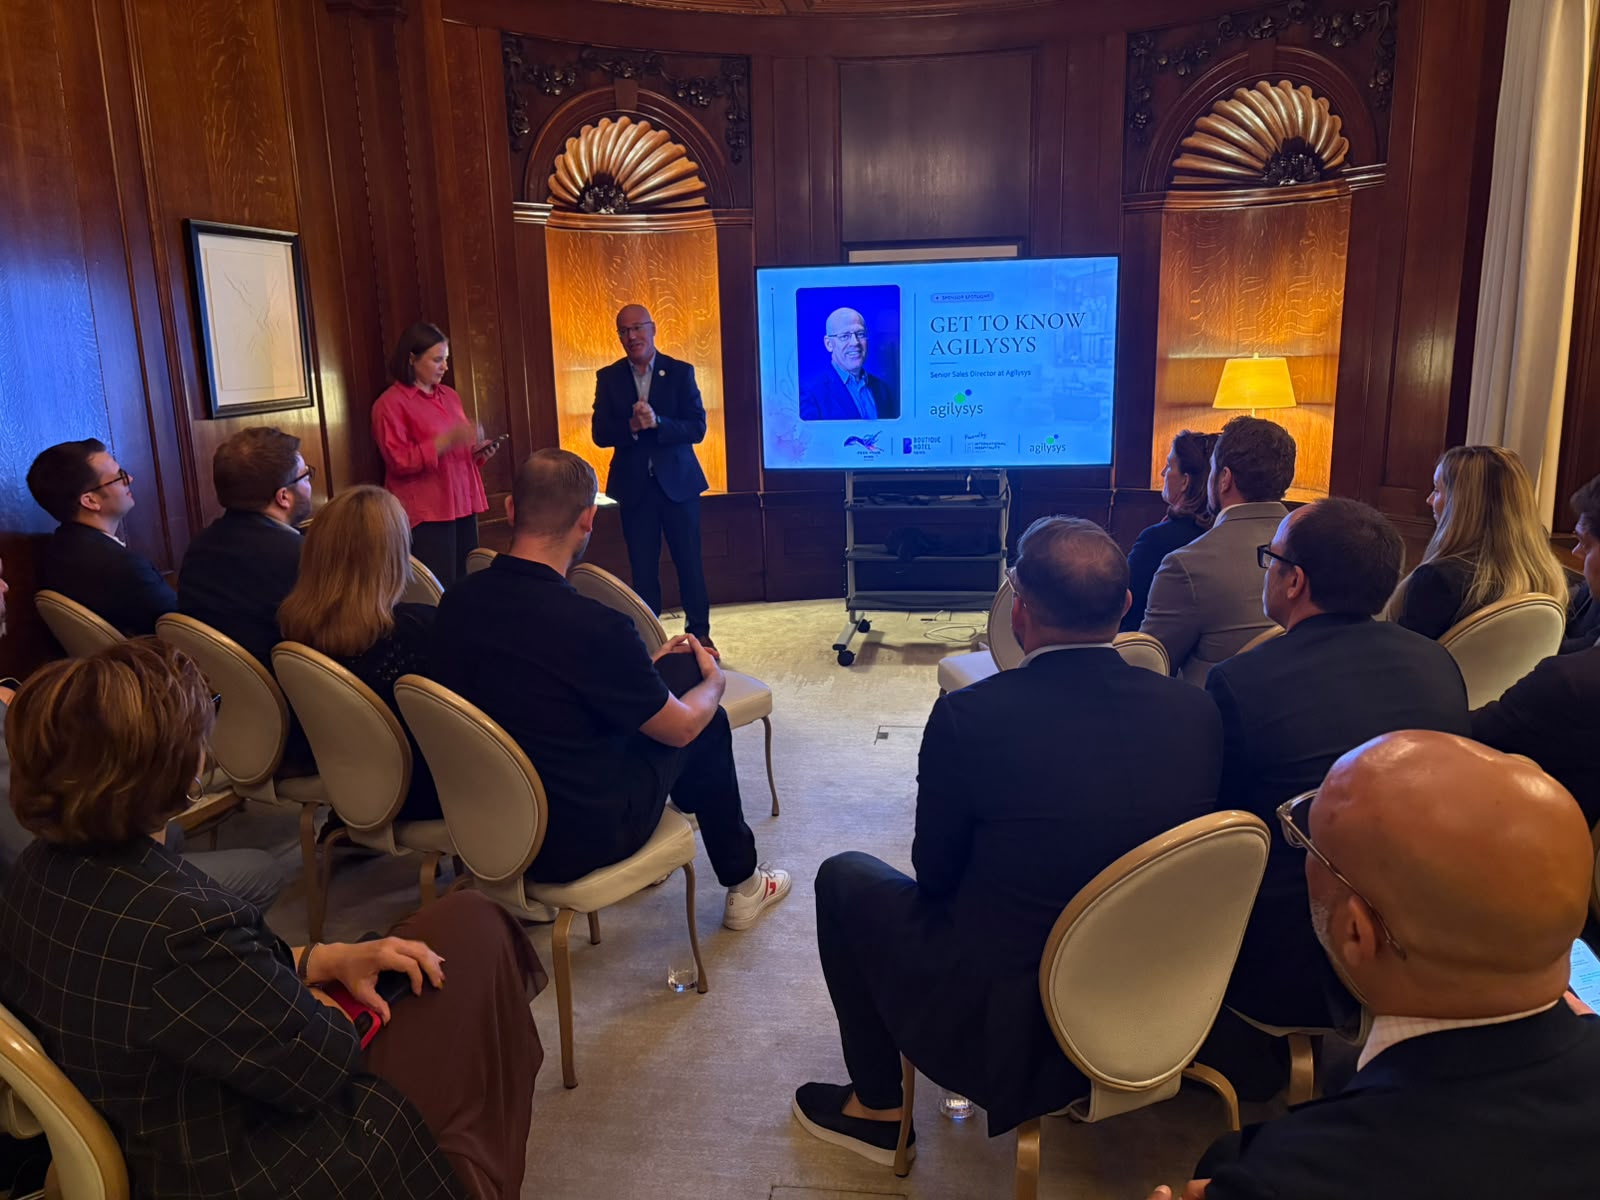
Boutique Hotel News held its latest Feed Your Mind hotelier breakfast in partnership with AHV Associates, hosted at the House of Lords.
Feed Your Mind events are co-hosted, content-driven roundtable discussions over breakfast, lunch or dinner. Each event is designed to provide hotel service providers with the opportunity to inform and shape the market.
The latest event, in partnership with AHV Associates, focussed on the hotel transaction market.
Despite a challenging macroeconomic environment, the hotel sector has shown strong underlying operational performance and resilience. Andrew Harrington of AHV shared that, while overall investment volume is down 10 per cent, it remains 11 per cent above its 10-year average, with two-thirds of transactions concentrated in the upscale and luxury segments.
Historically, private equity funds have aimed for net asset value (NAV) distribution rates near 20 per cent annually. This is increasingly unachievable and high interest rates and debt service costs have slowed asset sales, widening the bid-ask spread – most notably in tertiary and regional markets compared to a tighter and competitive London market. As a result, funds have returned substantially less cash to limited partners (LPs), bringing distribution yields down toward single digits, roughly around seven per cent. While large private equity remains active mostly in major platform acquisitions, family offices, property companies, and UHNW/foreign investors with long-term investment horizons have emerged as the most active buyers.
Debt dynamics and incoming refinancing remain obstacles, particularly with interest rates predicted to rise in the coming months. Lenders have so far favoured “amend and extend” flexibility over enforcement to keep stress under wraps. However, as LPs reach their patience limit over low distributions, future market distress will likely be driven by investor fatigue rather than poor hotel operations. While private equity powerhouses like Blackstone and Brookfield can set up internal continuation funds to hold on to quality assets, smaller owners facing expiring debt will have little choice but to restructure or sell.
Meanwhile, operators face considerable headwinds: business rates, National Insurance contributions (NICs), energy prices, and incoming local visitor levies are making it difficult to maintain margin. To off-set cost pressures, hoteliers are choosing to close F&B venues, repurpose underutilised M&E space, and lease the space to external operators. A five-year general backlog in CapEx investment since COVID and high construction costs will force tough decisions on whether to hold, refurbish, or sell in the coming year.
Companies represented include: Albertson Solicitors, Barclays, Beaufort Capital, BlackRock, Blue Key Capital, Bridges Fund Management, C1 Capital Partners, Cedar Capital Partners, Christie & Co, Clermont Hotel Group, Dalata Hotel Group, Essendi, Firethorn, Keystone Law, KKR, L&G, Maya Capital, Nestor, Numa Group, Schroders, TFE Hotels, Village Hotels, Westmont, Wyndham Hotels & Resorts, Zunikh, and more.
For further information about our Feed Your Mind events, click here or contact Katie Houghton at katie@internationalhospitality.media / +34 711 02 42 31.